
An email arrived in Austin one morning in January, carrying photographs of a roof taken from the air.
The policy attached to that roof had been running for more than a decade without a single claim against it.
No inspector had come out to the house. No ladder had gone up against the gutter.
The trees, the images showed, had grown too close to the shingles for the insurer’s liking.
What happened next cost real money, and the whole thing was entirely legal.
What it cost and how it ended
The homeowner is Tracy Gartenmann, and the notice told her plainly that the coverage would not be renewed.
She had filed no claims in all that time. The only evidence against her was a picture from above showing limbs reaching out over the roof.
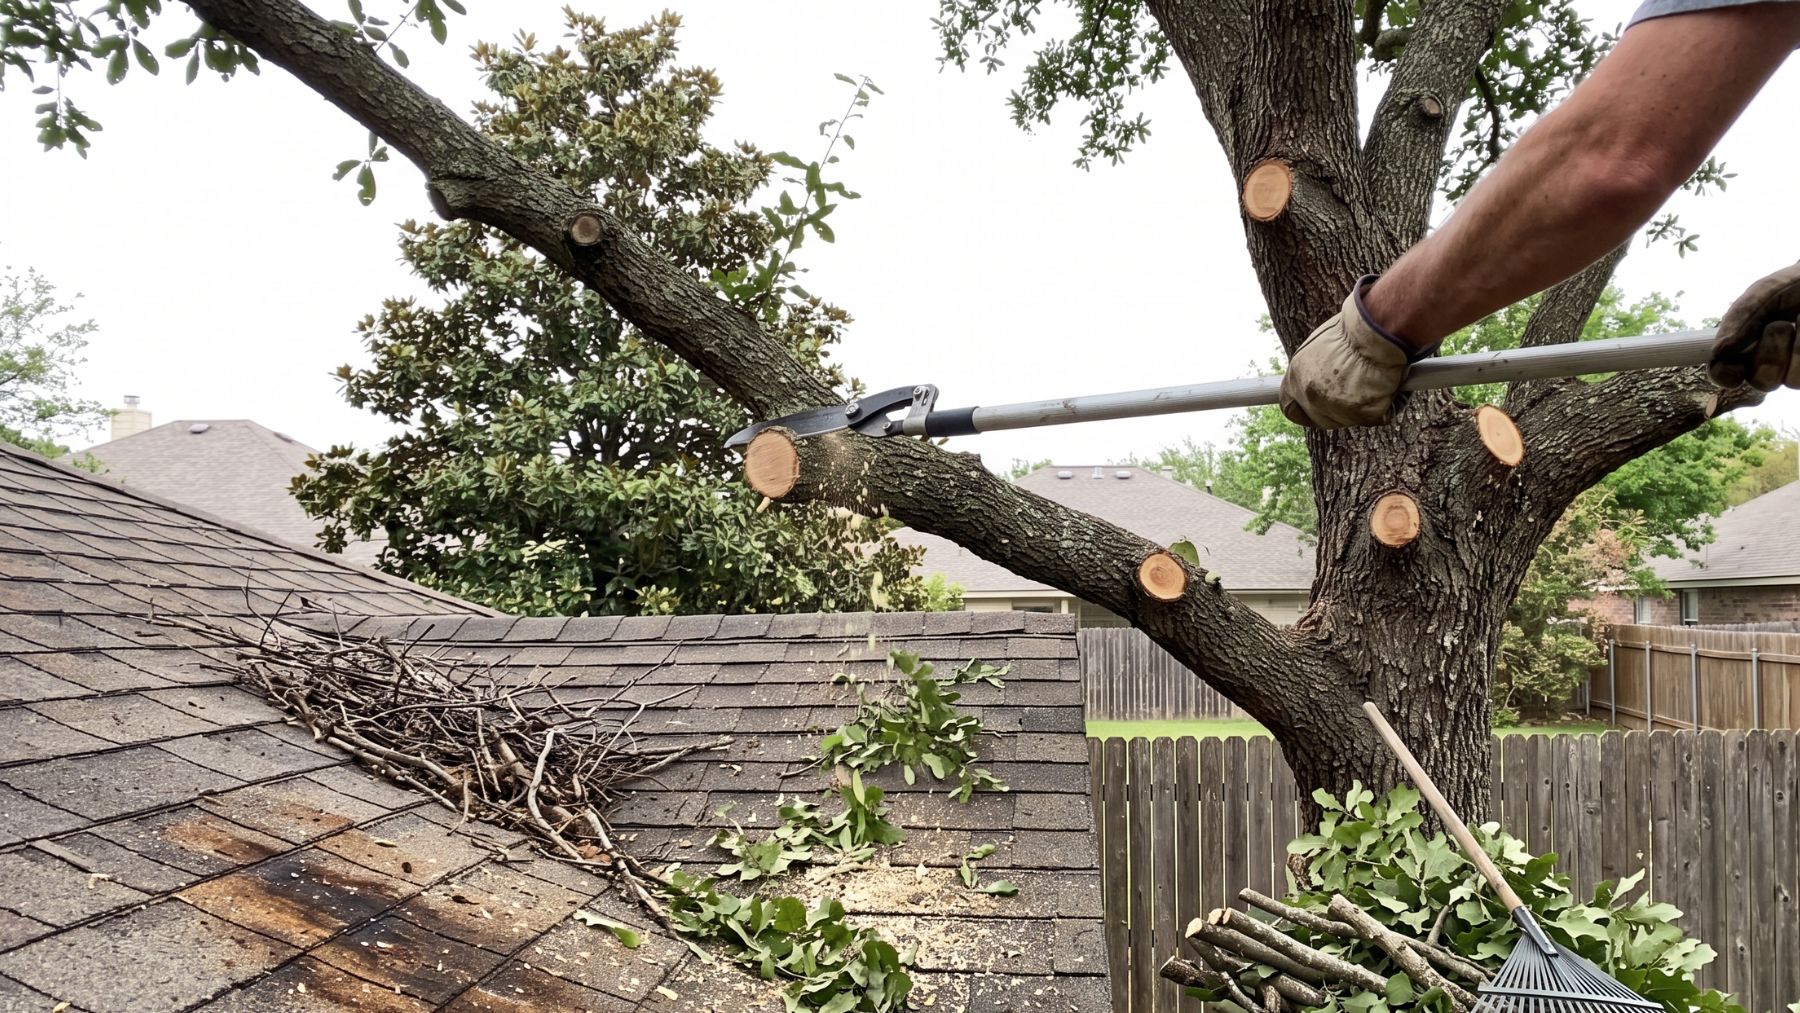
So she hired a landscaping company and paid 3,000 dollars out of her own pocket to have the trees cut back.
Then she photographed the pruned branches herself and sent those pictures back to the insurer as evidence.
The policy was renewed days before it expired, which means the system worked exactly as designed once somebody pushed.
Since 2023, at least a dozen homeowners in the state have filed formal complaints over decisions reached this way.
Texas wrote the permission into law
The uncomfortable part of all this is that nobody broke a single rule.
State law explicitly allows insurers and the companies working for them to fly private property in order to write and renew policies.
That permission was added by a bill passed in 2017, and it has sat in the statute book ever since without much attention.
So the aerial images were lawfully taken and lawfully used, and the homeowner had no standing to object to the flight itself.
What she did not have was any automatic right to see the pictures, ask what exactly they showed, or have somebody drive out and look for themselves.
The gap is not between what is legal and what is not. It is between what a camera sees and what a person on a ladder would confirm.
How wide the eye actually is
The scale of this is easy to underestimate and just as easy to overstate, so the numbers are worth getting right.
One imaging company says its coverage reaches almost every American, putting the figure at 99.6 percent of the country’s population.
Another analytics firm supplies insurers who between them hold at least a fifth of the entire home insurance market.
The figure most often quoted is that about 70 percent of home insurers use aerial photography, and that is not what was measured.
The actual survey said roughly seven in ten are using, developing or merely testing artificial intelligence and machine learning for underwriting and property inspection.
That is a much broader statement, and it includes companies still only experimenting with the idea.
What the software looks for
The detection list itself is unglamorous and, for the most part, entirely reasonable.
Aging roofs, overhanging limbs, debris, chimney damage and general upkeep are the standard targets, as the case in Austin illustrates.
The trouble is resolution and interpretation. A tarp over a woodpile, a shadow lying across shingles or an old leaf stain can all read as damage from 1,000 feet up.
A homeowner cannot argue with a file they have never been shown, which is where most of these disputes stall.
The advice from people who handle these cases is blunt, which is to ask for the photographs and the report the decision rested on, as the guidance around the practice sets out.
The same asymmetry turns up around an offshore array or a fenced solar site, where one party holds the measurements and the other holds the consequences.
Where the rules are moving
Two states have started closing that gap, and one of them has already finished the job.
Massachusetts regulators have issued guidance saying cosmetic roof conditions visible from the air cannot on their own justify cancelling or declining coverage.
Where the imagery does not clearly establish the condition of a roof, the state expects further review, including a physical inspection of the property.
California has a bill in front of it that goes further, requiring advance notice before images are taken and giving homeowners the pictures on request.
It would also bar the use of imagery older than 180 days for these decisions, attach the images to any nonrenewal notice, and let a policyholder demand that somebody verify it in person.
Until that spreads, the practical move is the one the Austin homeowner worked out without being told, which is to photograph your own roof before somebody else photographs it for you.
Read the whole thing?
Get the week's signal, not the noise
Our sharpest reporting on energy, climate and nature — free, once a week.


